TED

I LOVE TED.

No, I’m not coming out of any closet. I’m talking the annual Technology, Entertainment, Design (TED) forum. It started out (in 1984) as a conference bringing together people from those three worlds. Since then its scope has become ever broader.The annual conference now brings together the world’s most fascinating thinkers and doers, who are challenged to give the talk of their lives (in 18 minutes).

For example, here’s Richard Dawkins’ “Queerer than we can suppose: the strangeness of science.”

Or here’s Hans Rosling’s “Debunking third-world myths with the best stats you’ve ever seen” and his New insights on poverty and life around the world.

Or how about Howard Rheingold’s “Way-new collaboration”There is, if done well, very few things as stimulating as an excellent speech. Thank you TED for providing a way to revive this marvelous genre by sharing it on the internet.

Go to TED. But beware: you may end up unable to stop listening to one fascinating idea after another.

Share

Similar Posts

  • Crow Journal, day 1


    I decided to put my money where my mouth is. Or at least some peanuts and cheese. I want to make some friends with a couple of crows or ravens.

    I’m a little hesitant. One or two buddies, okay. A freaking tribe swirling around the house, pooping on man and beast, or, horrors, tormenting the cats and demanding food–well, that’s something to write about, isn’t it?

    Zing.

    Besides, I’ve only ever seen a pair. How many friends can they have?

    So I braved my fears and gathered six raven and crow calls from the internet. Then I put them in a play list, stuck my speakers in my office window, and began broadcasting crow. The mixture probably said something like, “Hey, there sweet momma, get off my branch you hawk turd!, can somebody pass me a napkin?” It’s got to pique their curiosity at least.

    With the calls running I set out some cheese and peanuts at the edge of the lawn out our basement door. It appears these folks eat anything and tend to like fatty food. When I go to Logan next I’ll get some potato chips.

    Results: 

    1. Three buzzards swooped up the slope and passed by.

    2. The herd of cattle down the hill and across the street all stood and stared up at the house.

    3. One of the cats came around to see what the commotion was all about.  Stuck its head through the deck railings to get a look down where the sounds were coming from.  

    I played the calls all during lunch. Nothin. So I turned them off.

    At about 3:40 PM I set out for my hike. Put out the speakers again and departed. On my way back down the hill at about 4:40 PM I saw the crow pair (or maybe they’re ravens) flying up the hill about 200 yards south of the house. They were dinking around in the air not trying to get anywhere fast.

    Hustled down and checked out the peanuts and cheese. Nothin. No sign of any visitors coming to investigate. Will try again tomorrow.

    Share
  • AIG bailout, risk, and writing

    With the current financial “crisis” I kept wondering what went wrong. Read this article on the AIG mess from the guys at the Motley Fool. That explaination of the AIG mess is very interesting. The other part of this current financial mess, the loaning-of-money-to-people-who-were-idiotic-credit-risks and the making-me-foot-the-bill-for-someone-else’s-assumption-of-ridiculous-risk, those two parts torque me.

    So why am I posting this in the Zing and Writers categories?

    Because it IS zing to me. You could write a high-finance thriller about this. You could write about a character who leveraged himself silly and is about to lose it all–in a smaller sense. You could write, hey, wait a minute. I just read a book about something similar–THE CHAIRMAN by Stephen Frey. It’s a 2.5/5 star book. Good enough that I had to finish it. Although not good enough to make my recommendation list. 

    The point is that stories are about problems and conflicts. And this understanding of the insurance industry provides some fertile ideas for both problems and conflicts.

    And since I can’t get the blasted link to work, here’s the full deal.

    AIG’s Failure Is So Much Bigger Than Enron
    By Andrew Sullivan, CFA
    September 17, 2008 Comment (54) Recommend (124)
    Enron — reviled, fraudulent Enron — destroyed more than $60 billion of shareholder value.

    AIG (NYSE: AIG), which the government just took over, has destroyed $180 billion already — and it almost brought down our entire financial system.

    We don’t know money
    Which is ironic, given AIG’s old television commercials, in which the giant letters “A I G” displayed on the screen while text flashed underneath that culminated in the following phrase — all in capital letters:

    WE KNOW MONEY

    There were no smiling couples, young children at play, or lounging retirees. No, AIG was above that — it was better than that.

    But here’s a news flash, AIG: You don’t know money.

    If you did, you’d have realized a few things. Insurance is terribly simple, as long as you follow the Three Rules:

    Price your risk correctly.
    Invest conservatively so you can pay out claims when they come due.
    Don’t do anything else.
    Sit back and collect the spread. That’s it, folks.

    Seriously, that is it. Ask Warren Buffett, and he’ll probably tell you that if you follow those three rules, you’ll be fine. You won’t be the biggest or fastest grower, but you’ll be absolutely fine.

    The problems come when you get greedy and aren’t satisfied with the spread. And your greed can lead to certain actions that aren’t stated anywhere in the rules, including:

    Diversifying into fast-money proprietary trading.
    Leveraging your company 11-to-1.
    Neither of these is a goal of a well-run insurance company, yet AIG embraced both with open arms.

    Diworsifying
    But AIG self-destructed not because it screwed up in its insurance business. It didn’t fall into the trap of mispricing risk, as so many other insurers over the years have done. It also invested premiums fairly conservatively. So it followed Rules 1 and 2.

    Where it slipped up was in Rule 3. See, the folks at AIG thought they were so smart at insurance that they could start other capital-markets businesses … including proprietary asset management in things such as commodities, currencies, energy, interest rates, and the selling of default swaps on collateralized debt obligations (CDOs).

    This strategy worked beautifully — for a while. AIG created a separate business segment called Financial Services to trade in the aforementioned assets. This business had $204 billion in assets at year-end 2007, up from $60 billion in 1998.

    Operating income surged from $900 million in 1998 to $4.4 billion in 2005. Some of the moves it made were brilliant, such as the purchase of ILFC, an aircraft-leasing business. But the other trading businesses were the Medusa that turned the whole company to stone.

    Let me make one thing clear: Proprietary trading isn’t bad, in and of itself. Warren Buffett engages in it. But just like atomic weapons in the wrong hands, proprietary trading can do a lot of damage. The problem is when you start to get aggressive and don’t heed proper risk — when you start to speculate instead of invest.

    And there’s one other critical ingredient for disaster.

    The “L” word
    As in “leverage,” the sharp knife in corporate seppuku dramas. Leverage is, by my estimation, the No. 1 reason why companies fail.

    And compared with its peers, AIG had one of the sharpest knives around. Here’s how its leverage (assets to equity) stacked up against other insurance operations as of December 2007:

    AIG: 11 to 1.
    Markel (NYSE: MKL): 4 to 1.
    Berkshire Hathaway (NYSE: BRK-B): 2 to 1.
    Montpelier Re (NYSE: MRH): 2 to 1.
    Travelers (NYSE: TRV): 4 to 1.
    White Mountains Insurance (NYSE: WTM): 4 to 1.
    Chubb (NYSE: CB): 4 to 1.
    I would love it if someone gave me a rational, believable explanation of why leveraging your equity 11-to-1 is a good thing for an insurer. The sole job of an insurance CEO is to ensure that his or her company stays in business; the CEO’s job has nothing — absolutely nothing — to do with growing profits every year in a steady, smooth line.

    Surprises in insurance are almost always negative, so simply staying solvent is the overriding priority. A company can do just that by following the Three Rules.

    Two years ago, a few of my Fool colleagues had an interesting conversation with Chris Harris, the chief investment officer at reinsurer Montpelier Re. Harris noted that Montpelier invested its float primarily in U.S. Treasuries, Fannie and Freddie bonds (back when they were considered safe), and the like.

    When asked why he didn’t invest more aggressively, Harris said the company believed that it got all the risk it could handle on the other side of the fence, insuring against megacatastrophes.

    Even if you disagree, as an investor you have to recognize the judiciousness in this way of managing one’s business. An insurer that has to pay big claims from hurricanes Ike and Gustav and Typhoon Sinlaku — and additionally worry about the rapid decline in its investment portfolio as a result of the higher level of risks it has taken on — has a big problem.

    That insurer, folks, is AIG. And that big problem is now yours and mine.

    This really is bigger than Enron
    The edifice Hank Greenberg built has all come crashing down. Apparently, AIG didn’t realize that almost 40 years of 15% growth multiplied by a big fat zero equals just that: zero. It didn’t consider that its leverage left it exposed to a liquidity crisis, and it didn’t consider that its non-insurance businesses could bring down the whole company.

    In all fairness, management did not realize how much exposure it had to CDOs backed by subprime loans. This may or may not be true, but Buffett has famously stated that each one of these prospectuses has something like 15,000 pages, so it’s unlikely they were gone through in any great detail.

    But investing in things you don’t know is a huge risk, right? And that risk was compounded by having so much leverage. The fact is, the more leverage you have, the more careful you must be with the investments you hold, because your own capital structure is that much riskier.

    AIG did nothing of the sort. And so even though it has a rock-solid, wonderful insurance franchise, its greed and lack of care in its investing decisions took down one of the world’s great companies.

    What a shame. What a shame for all of the investors who lost billions thinking that this company was conservative. What a shame for taxpayers like you and me. What a shame for the United States’ reputation as a beacon of financial stability and conservatism.

    For Fool.com’s continuing coverage of this week’s events, check out “The Biggest Financial Story of the Past 50 Years.”

    Andrew Sullivan has no financial interest in any of the companies mentioned. Montpelier Re is a Motley Fool Hidden Gems selection. Markel and Berkshire Hathaway are Motley Fool Inside Value recommendations. Montpelier Re and Berkshire Hathaway are Motley Fool Stock Advisor picks. The Motley Fool owns shares of Berkshire Hathaway and has a disclosure policy.

    Share
  • Australian Uses Oil Background to Harness the Seas

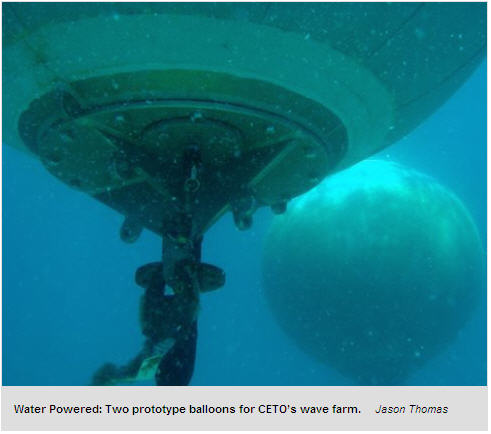
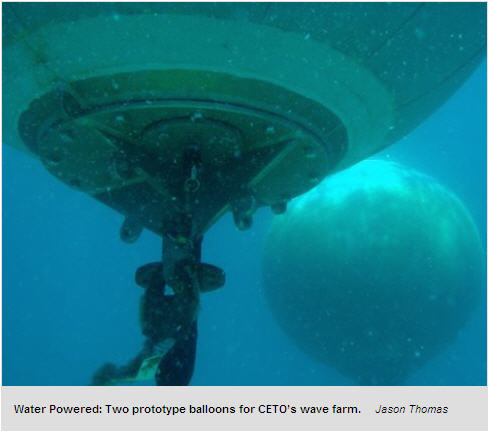
    This is a fantastic article summarizing some key issues with wave energy and the solution Alan Burns, an oil bloke from Australia, has come up with. It appears he’s taking lessons from his expertise in off-shore drilling (it’s safer to work on the bottom of the sea) and applying it to wave energy. It’s a must read.

    http://www.popsci.com/kalee-thompson/article/2008-09/burning-tide

    No ideas yet on how to use this in a story. If you have any, post in the comments section.

    Wait, what if our hero is an inventor like Mr. Burns? Naw, what if we actually do go to the seas? It seems like a no-brainer. So we go to the seas. And our hero is the guy who is replacing parts. Humm, maybe. Of course, if our power generation is out there in the sea, then a perfect target for a terrorist is the pipe pumping the water in. Or what if they find a sea wreck while installing a huge one of these? And would the ocean floor suddenly become real estate? What kind of agent would sell it? Hummm

    Share
  • |

    Monks in Mormonland (and their honey)

    We just visted the Abbey of our Lady of the Holy Trinity this week with my family. It’s nestled on over 1,800 acres of some the most beautiful country in Utah.

    I think almost every religion demonstrates virtues we can all learn from. The dedication of these good men to their beliefs and vows to God is one such example.  As is their decision to live simply. And their creamed honey blends, which you can order from their website, are delicious! So far the maple honey is my favorite. Here’s a 2 minute National Geographic video about this abbey.

    Share
  • The path to?

    Is this not delicious? I found it on istockphotos.com and couldn’t stay away. I want to be on that trail. I want to know what’s around that bend. Holy moly, the feeling of this photo is just marvelous.

    So I bought a copy. It’s by stellalevi.

    Wicked Tree Path

    Zing, Baby!

    Share
  • War Predictors

    What’s the best predictors of which nations are most likely to go to war or exhibit instability?

    Up until now these three factors were assumed to be the most predictive: poverty levels, lack of democracy, and the nation’s adherence to Islamic values. However, Valerie Hudson and the folks of WomanStats have found a fourth factor that is a better predictor:

    These results indicate that if a scholar or policymaker had to select one variable—level of democracy, level of wealth, prevalence of Islamic culture, or the physical security of women—to assist them in predicting which states would be the least peaceful or of the most concern to the international community or have the worst relations with their neighbors, they would do best by choosing the measure of the physical security of women.

    I found it interesting that their research indicates of all the predictors prevalance of Islamic culture is the weakest. So much for the idea that Islam is the bogey man.

    Before presenting their findings, they make a theoretical case by synthesizing insights from evolutionary biology and psychology, political sociology, and psychology. When summarizing the ideas from evolution, they state:

    Evolutionary theory suffers from two common misconceptions. The first is that evolutionary predispositions are intractable. No evolutionary theorist believes this. Richard Dawkins explains, “It is perfectly possible to hold that genes exert a statistical influence on human behavior while at the same time believing that this influence can be modified, overridden, or reversed by other influences.” The second misconception is that evolutionary theory posits static and essential characteristics for males and females. This has been debunked as well. In debunking this myth, Theodore Kemper notes, “Across the spectrum of the social sciences, the results show that females are not essentially pacific, retiring, unaggressive, lacking in motives and psychological need for power and dominance. While successful ideological socialization may persuade many women that this is true of themselves, it is not biologically true.”

    These misconceptions are very interesting indeed and should be remembered when examining genetic based arguments for all sorts of behavior. When they discuss social learning theory from psychology, they reiterate this point:

    First, social learning psychologists argue that biology does increase the likelihood that a child will engage in aggressive or violent behavior, but does not guarantee it. For example, twin and adoption studies find that genes make a small contribution to various forms of antisocial behavior compared to environmental factors. For example, while finding that having a biological parent who was antisocial increased the risk for antisocial behavior to be seen in an adopted child, these same studies also demonstrated that having a disrupted home environment contributed more significantly to the risk for a child to engage in antisocial behavior.

    They then discuss specific environmental factors that lead to violent behavior against women. It’s a fascinating article. I highly recommend it. You can find the original, “The Heart of the Matter: The Security of Women and the Security of States,” in Harvard university’s International Security, volume 33, issue 3.

    Okay, okay, so how do the countries rank? Here’s a summary from the Deseret News:

    A WomanStats map reveals highest levels of women’s physical insecurity in the Middle East, India, much of Africa, Brazil and Mexico. On a Violence Against Women scale, the United States sits smack dab in the middle, at a level 3 on a 5-point scale, with moderate levels of domestic violence and rape.

    Share