How to Get Rich: Spend

No, really. It’s true. You just have to spend smartly. And in a special way.

Over the course of your life, if you make what the average American does, more than a million dollars will flow through your hands.  And yet so many of us don’t feel rich.  That’s because money is like the Gingerbread Man.  Turn your back on it, and it’s out the door, rudely taunting everyone as it flies by.  And then it gets eaten by a fox. Such a waste.

But it doesn’t have to be.

Let me share with you THE best method I’ve found for managing my money.  It takes tons of anxiety out of spending and saving.  And, if you’re a Dave Ramsey fan, it is the one thing upon which everything else he teaches depends.  If you’re not a Ramsey fan, it doesn’t matter. After getting a job, this is the first thing you must do to get rich.

Here’s the big secret. It has three parts:

1)     Decide how much you’re going to spend on various things BEFORE you spend it

2)     Make what you have left in each spending category EASY to track

3)     Manage the things you can’t foresee

To do the first two parts, you’re going to create a special kind of spending plan. We won’t use the term “budgeting” because “spending” is so much more fun, and because that’s what we’re going to do anyway. To understand how to do this, you need to watch three videos.

Before you do, please know I earned a Masters degree in accounting.  I’ve used Quicken for more than twenty years.  Neither of those things has helped me manage my money like this simple method.  If you’re looking for a better way to manage your money, this is it.

First, watch this video to get an overall idea of how this method works.

Note: you can use actual envelopes and cash for everything if that makes you happy, but you really don’t need to.  The idea is to think of pre-allocating your monthly income to categories of expenses AND then having an easy way to track what’s left.

Now, watch this bubba explain how he does it.

But John, didn’t he say the same thing?

Basically, but he has a fun accent. Besides, it’s good to see another example. And please note again: you don’t have to use actual envelopes and cash, although many swear by them.

Finally, watch this one. No, it’s not just another repeat. There are some additional important ideas illustrated here.

This video brings up the idea of why simply tracking an overall account balance isn’t very helpful. It also shows you WHY envelope categories are–they make it immediately apparent how much money you have to spend for a thing.  If you just use Quicken to track what you spent (looking in the past), you’ll run into troubles.  Let me tell you, I know this from experience. We use Quicken, and have for years, and plan use it for some time to come because it makes taxes and bank reconciliation a snap.  But Quicken only tracks what you spent.  Tracking, as important as it is, is not the key to success.  The key is pre-allocating BEFORE you spend.  And then tracking so you know what you have left in that category.  And making that tracking EASY.

The final thing you have to do is manage the things you can’t foresee because things rarely go exactly to plan. Unexpected things ALWAYS come up. Your daughter will crash the car. Your husband will get appendicitis. You will forget that you had a $200 school sports expense.

Okay, fine. Things happen. But how do you manage them if you can’t foresee them?

If it’s really small, you simply adjust your plan. For example, if you need $30 more in food, you can transfer it from fuel if you have some extra there.

You manage larger things by building up an emergency fund. Ramsey suggests starting with a $1,000 emergency fund and then trying to get two to three months of living expenses—about $10,000 to $15,000 for most people. Unexpected things WILL happen and cost your money. So build up some cushion to take care of them.

Finally, you manage the really large things by getting proper insurance. This is what insurance is for. The types of insurance you need include (1) homeowner’s or renter’s, (2) auto, (3) medical, (4) long-term disability, (5) long-term care (for those 60 and older), and (6) life insurance. You may add true identity theft insurance as well.

Okay, so that’s the overview.  If you want to try this, here’s how you do it.  It’s fairly easy. 

STEP 1: get your head straight

Resolve that you will NOT use credit for anything. You will not spend any money you don’t have.  You will not put another dime on a credit card, and this despite the fact that the plastic devil companies are begging you with offers almost every day to sign up for their cards. (Hum, I wonder how they afford all that junk mail.) If your monthly bills are greater than your income, then we have to fix that first.  But the new law of the land is zero new debt.

Next, always remember to allocate your money to these categories first—shelter, food, adequate clothing, and adequate transportation.  This means if you have a crunch month, you would NOT pay credit card bills before food, even if you work for Visa.

STEP 2: get your blank sheet & pencil

Get out a piece of paper and pencil (not a pen) or open an Excel spreadsheet.  Whoa, that was an easy step.

STEP 3: list your monthly income

List your expected monthly income at the top from all sources.

STEP 4: list your spending categories

List your spending categories. You’re going to split them into two groups.

The first group goes right below your income and includes all of your recurring monthly expense/spending categories. Not the amounts you spend. Just the categories. Things like mortgage, electricity, phone, groceries, dining, etc. Make sure you include some entertainment/fun money.

The second group goes below your recurring monthly expenses and includes all of your major annual periodic expense/spending categories. Things like Christmas, vacation, clothing, kids back to school stuff, etc. And things you want to save for—a couch, iPhone, car, etc. Your emergency fund goes here as well.

If you need help thinking up categories, use these Ramsey resources: Monthly cash flow plan forms and Monthly allocated spending plan form.

STEP 5: Fund your categories

Decide how much you will spend in each category this month.  You should have 0 dollars when you get to the bottom of the sheet.  Spend (allocate) every dime BEFORE you start the month.  You’re going to do this at the beginning of each month.  And you will probably have to adjust it a couple of times during the month.

You will probably have categories that don’t get any money this month.

You will also have categories that get money, but you won’t spend any of it this month.  These are your periodic expenses.  Your goal is to have the cash up front to pay for them, so you have to save for them.  Remember, you are NOT going to take on any new debt. 

For example, if you’re saving up for Christmas, you allocate some money for that out of this month’s funds and TRANSFER it to savings.  Then it will be there when you need it.  You could draw the cash out and put it in an actual envelope, but you don’t have to.  Just as long as you keep a record of the total amount in savings and what it’s all supposed to be for, i.e. total savings in July = $1,000: $500 for back to school, $200 for Christmas, and $300 for my trip with kids to Six Flags in 2013.

STEP 6: mark the “watch” categories

Some of the categories you need to watch closely, and some you don’t. The ones you need to watch closely will be your “envelope watch” categories. 

The categories you don’t need to watch as closely are those that are automatically taken out of your account each month.  And those you will write a check once a month for.  These things include mortgage, car payment, electricity, etc.  These are NOT categories you need to use actual envelopes for.  You can track it on paper or in the spreadsheet. Not much happens with these categories. 

But there are other categories that you’re going to be spending throughout the month, and it’s easy to over spend if you don’t track them.  Groceries, dining, entertainment, gasoline, a specific vacation, etc. are all categories that you make multiple purchases with each month and are flexible/discretionary and need to be watched closely.  So while everything is tracked in a category/envelope on paper or on the computer, you’ll track these with either a real envelope and cash or a virtual one using that free software you saw in the third video or a piece of paper with a running category balance in your wallet.

STEP 7: have fun and spend!

Now go out and spend!

Before spending, check your envelope.  Do you have enough money?  If you do, spend and be happy.  If not, save up for it or find a way to save money in another category and adjust so that you’re still spending the same total amount.  Never spend what you don’t have.

If you feel you need something not planned for, well, you have to get it later OR transfer something out of another envelope.  I just make myself wait a day or three, and usually the urge to buy, Buy, BUY! goes away, and I see I don’t “need” it right now.  Or maybe a more affordable option presents itself.

If the kids want something, and you feel guilty you can’t give it to them, just tell them what’s in the envelope/category, and tell them they can save for it or choose something else in that category that will fit with what you have left.

If you’re tracking envelopes virtually or using the paper balance in your wallet, you MUST update your envelope AFTER every purchase so you don’t spend more than you have. If you find you just can’t seem to remember to do this, go to the cash method.

That’s it! 

Of course, that’s not quite it because even though it’s easy, if you haven’t done this before, it might take some adjustment.  Give yourself a month or three to get it down.  Because when you do, it WILL produce great results and peace. It’s doing that for us. 

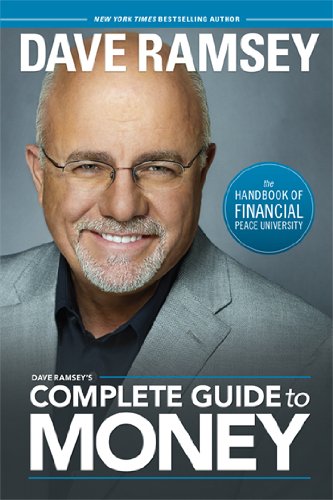
If you feel you need more info, I suggest you read Dave Ramsey’s Complete Guide to Money.  Here’s the first chapter to sample: Complete Guide To Money sample chapter.

Happy spending.

EDIT: here’s another video to watch: http://www.youneedabudget.com/.  Then read about the method: http://www.youneedabudget.com/method. This one highlights the idea that you need to make sure you realize that things will happen that you cannot foresee. No plan survives contact with the enemy.

Share

Similar Posts

  • A Wowser Mouse & Financial Peace

    Dis Eez A Mouse

    I’m a Luddite, which means that even though I work in the software industry, I do not rush out to purchase the latest and greatest gadget.  Our family computer, for example, is running Windows 98, primarily because we purchased the computer itself in 1999.  In human years that computer is like 432 years old.  Maybe we’ll retire the old boy this year.  The point is that I don’t like to churn through tons of gadgets.  I want something to work.  I want it to work well.  And then I want to use it for a long time. 

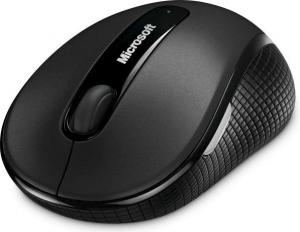
    Recently, my mouse started acting up.  So I went out and found a new one.  I settled on a Microsoft Wireless Mobile Mouse 4000.  It comes with three parts: the mouse, an AA battery, which is supposed to last for up to ten months, and a tiny transceiver you insert into one of your computer’s USB ports.  The mouse has a great hand-feel.  The clicks are smooth.  If you want to take your mouse with you somewhere, there’s an easy storage slot inside the mouse for the transceiver.

    But the best thing of all is its BlueTrack technology.  This is not an ancient mouse with a track ball that you have to clean every so often.  It’s an optical mouse.  But unlike earlier versions of optical mice (why do I have a terrible urge to use “mouses” or “meece”?) that didn’t work very well on a number of surfaces, this BlueTrack technology works like a charm on everything I’ve tried it on, including glass. 

    You need a new mouse?  This is a good one.

    Dave Ramsey’s Complete Guide to Money

    If you’re like 70% of America, you are living paycheck to paycheck, which means that if you or your spouse (assuming you have one) were laid off, you would probably have difficulties meeting your mortgage the next month.  If you didn’t go into default on the house, you certainly would on other payments and bills. 

    You also have very little retirement. 

    You probably have around $7,000 in credit card debt.  Maybe a lot more.

    You also have a car payment or two.  Or, heaven forbid, a lease. 

    You might be house poor—the house payment is so large you can’t seem to do anything else. 

    You might have creditors hounding you. 

    You might be one of those folks throwing their money away on the lotto instead of investing it. 

    Did you know that if you invested $50 a month, an average of what many lotto players spend, in the stock market for 40 years, you’d very likely end up with $316,000 in the bank  (over the last 40 years of ups and downs, the annualized return of the market was almost 10%). You would have put in only $24,000 over that time period, which means you would have made $292,203!  But instead, if you’re a lotto player, you just throw all that out the window.  (No, you’re not going to win; not even maybe in your dreams.)

    You probably think your kids will have to take out loans to go to college. And you think that’s a good idea.  In fact, you probably think it’s a good idea to have a credit card just in case there’s an emergency because you don’t have any savings to cover any emergencies.

    The list goes on.  The sad part of this is that our finances cause us average Americans a lot of stress in our lives and marriages and families (even if we’re in denial) and very often heartbreak. 

    I know that a lot of us look at our financial chains and throw our hands up in despair—what can I do?  The mountain of debt and bills are just too high.  Besides, this is how everybody lives.

    But it’s not.

    There is a way out.  And it doesn’t matter how old you are, it’s not too late.

    Dave Ramsey has written his hands-down best book ever, which will take you step-by-step through the process of turning a financial mess into financial peace.  He’ll do it in a down-to-earth easy-to-read style. No confusing ten dollar words that make your head spin.

    Ramsey himself went through financial hell.  He was the guy that made all the mistakes with his money.  Lost everything.  Had collection agencies coming after him.  Didn’t know how he was going to feed the family.  He turned that all around.  Yes, he’s a millionaire, but more importantly, he has been working for the last twenty years to teach regular people with regular jobs the simple principles that lead to financial peace.  They’re becoming debt free and working their way towards huge net-worth.  

    You want a step-by-step plan?  You want to educate yourself about money and family finances from one of the nation’s leading experts?  Then go and purchase Dave Ramsey’s Complete Guide to Money today and start reading it.  You will not regret it.  If you already have his Total Money Makeover and don’t think this will be worth it, think again.  This goes into all sorts of things the Total Money Makeover doesn’t.

    Be free, people.  Be free.


    Related Stuff

    Look at the links and the video.

    Share
  • Sherlock Holmes, Mission Impossible, The Art of Shaving, Wages

    Sherlock Holmes & Mission Impossible

    I have been looking forward to two movies this holiday season. One of them was as good as I’d hoped it would be. The other disappointed me because the story tellers forgot to make things clear. The two movies were Mission Impossible: Ghost Protocol and Sherlock Holmes: A Game of Shadows.

    I loved the first Sherlock Holmes movie—the story was intriguing and plotted well, the atmosphere and music were amazing, and the characters and relationships were even better. In fact, the movie presented some of the most delightful characters I’ve enjoyed over the last few years. So it was a no-brainer to plan in a date to see this new episode.

    Sherlock Holmes: A Game of Shadows provided the same great atmosphere and music as I enjoyed before. Holmes and Watson were as wonderful as they’d ever been. The film introduced a wonderful new character: Madam Simza Heron, a gutsy gypsy who you can’t help but want to know better. And it brought on Professor James Moriarty, the uber-villian. There was plenty of the wit that we enjoyed in the first one. It had all the elements to work.

    However, the film fell down in its plotting. There were many times when I had no idea why the characters were doing what they were doing or how it fit into the overall threat. At other times, it appeared Sherlock could have taken out the villain but didn’t only because it would have ruined the plot.

    The film makers also decided to kill off one of the characters, and therefore relationships, that had provided so much satisfaction in the first movie. And they did it without much fanfare. Who thinks it’s a good idea to kill off beloved characters like that? If you’re going to kill someone we love, you’d better make it meaningful and the core of the film. Alas, they didn’t.

    In fact, it felt like there was too much stuffed into this film. Cool ideas that couldn’t be explored or have much impact including facial surgery for spies, a lost brother, European politics, resistance fighters, a henchman we hardly see. The wonderful Madam Simza Heron didn’t play the pivotal role she could have. So unlike Irene Adler in the first movie who becomes central to the story, she’s more of a bit of the setting.

    If you loved the first film, you’ll have to see this. There’s a lot of good. But you must go knowing it’s a grade lower than the first film.

    Now, I stopped liking the Mission Impossible movies about thirty minutes into the second in the series. But the previews for Mission Impossible: Ghost Protocol intrigued me. I like Tom Cruise as an actor. And so we decided to give it a try.

    Mission Impossible: Ghost Protocol didn’t provide the atmosphere or super-delightful characters and relationships of Sherlock Holmes. But that’s not to say its characters were tepid. On the contrary, the cast was great with a lot of funny interplay. Furthermore, unlike some action films where everything seems to work for the hero, a lot of things go wrong for Tom Cruise’s character. These problems and his reactions are part of what make the movie.

    The story also provided plenty of “action” but did it in a new way. This is the first time, for example, I’ve seen a car chase in a sandstorm. And it was a fab chase. It’s also the first time I’ve seen a final battle in an automated parking lot. The director and writers did a good job choosing new twists on common action elements.

    But a story needs more than characters and new sights—the plot has to make sense. Especially when the plot takes center stage, which it does in action movies. And I’m happy to say that I never once wondered why our characters were doing something or how it affected the main threat. Furthermore, every one of the characters made a difference. The result was that I thoroughly enjoyed the film from start to finish. I can’t wait to watch it again. If you like action films, I think you’ll enjoy Ghost Protocol.

    The Art of the Shaving

    When I was on a mission in the Netherlands I was an idiot and did not take care of my face in the winter. I’d hop onto the bicycle with the temperature hovering around zero degrees (not counting the wind chill) and bike out with Fearless Companion to an area to meet with people or knock on doors. And I’d do it with hardly a thing covering my face and ears. As a result, I damaged my skin.

    So now when I’m exposed to cold, my face flushes and stays that way for some time even when I’m in a warm house. I can’t wear cologne. And I’ve had a love/hate relationship with shaving. I can’t stand the prickle of a beard and so love to shave, but I hate the fact that when I shave, my face turns the color of a tomato for four to six hours. And this is when I use shaving cream specifically formulated for “sensitive skin.”

    But then I walked into The Art of Shaving store in Fashion Place Mall and learned that those shaving creams designed for sensitive skins weren’t super gentle. They just numbed the skin so you didn’t feel the shave. The folks at The Art of Shaving suggested, of course, I use their product.

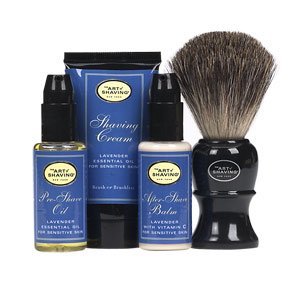
    I bought a kit (I’m a sucker for good sales pitches even when I know I’m being suckered) which included: a badger hair brush (they say it is optional, but I love mine and wouldn’t do this without it), pre-shave oil, shaving cream, and after-shave balm. They had five types to choose from: unscented, lemon, sandalwood, ocean kelp, and lavender. I selected the lavender because it was formulated for sensitive skin. At first I was worried about being overpowered with the smell, but was pleasantly surprised to find the scent as light as a feather. I didn’t need a new razor; they said my Mach3 was just fine.

    I came home with my bag expecting a huge dose of buyer’s remorse. Except after my first shave with their product, my face didn’t flush. Could this really be a product that worked? I wasn’t willing to make that conclusion at the time. But now, after about a month of shaving, I can honestly say that this is the best shave I’ve had in years. My face doesn’t flush. The after-shave balm does what a balm is supposed to do–soothe. There’s no alcohol burn. In fact, I use the after-shave balm on non-shave days. If your skin hates shaving, let me suggest you visit theartofshaving.com and order some product or go to one of their stores. I think you’ll also become a fan. 

    Info for Choosing a Career

    There are many things I wished I’d done differently when choosing a career. I wish I’d broadened my horizon on the horde of different careers possible. I wish I’d really looked at what the various careers earned on average. Luckily for those looking to select a new career today, Utah’s Department of Workforce Services compiles data on more than 700 occupational wages and shows you the average and median annual wage as well as the average for inexperienced folks in that occupation.

    Not only does looking through the list help you see options you might not have considered, it also helps you get a realistic expectation for what you might earn in that profession. Now, the list, although large, doesn’t show every possible occupation (FBI agent, Marine) or every permutation of the occupations shown. For example, there’s one line for accountants and auditors, but there are tax accountants, fraud accountants, security accountants, auditing accountants, etc. Nevertheless, this is an excellent list to begin a search.

    To get the list, go to this state website: http://jobs.utah.gov/jsp/wi/utalmis/default.do. Click on “Utah Occupational Wages.” That will open a page with a map of Utah. Click on the link on the right “Utah Occupational Wages” to get the Excel spreadsheet of all 700+ occupations listed.

    Share
  • Blindingly white and female!

    MaryLeonhardt_KeepingKidsReadingThe Guardian just published a report of a survey taken of 34 American book publishers and found that 79% of staff are white and 78% female. Or as The Guardian put it “blindingly white and female” as if it’s some kind of horror show.  The rest of the article bemoans the lack of diversity in publishing and our society in general and quotes the author of the study suggesting that these percentages should be monitored.

    Is anyone up in arms about appropriate diversity percentages in the NBA or NFL?

    Some might roll their eyes and ask me not to trot out that old chestnut. But it’s not a chestnut. It’s a point–nobody cares, me included. So why care about this? Many industries will be skewed toward one gender or race than another. As long as everyone has free opportunity to compete, who gives a flip?

    Maybe that still doesn’t satisfy. Okay, how about this. According to Humanites Indicators, approximately 70% of degrees in English language and literature in America are awarded to…women. And about 82% are awarded to Whites. I’m assuming these percentages are probably pretty good indicators for the gender and race of folks interested in working at publishing companies.

    If so, the survey results don’t reflect some white woman conspiracy at these publishing houses. They simply reflect the choices people make in college.

    By the way, did you know the United States is still 72% White and European. So it’s not surprising to see roughly that many Whites in these jobs. The numbers might be a little high, but minorities seem to be pursuing other degrees in greater numbers (compare the overall percentages here versus those with ELL degrees).

    This is not to say that we don’t want to welcome authors from all different background. We do. But if you want more men and more minorities, then maybe instead of monitoring publishers, you ought to start by seeing if you can attract more men and minorities to ELL degrees.

    Or even better yet, how about reaching out to more boys and minorities at an earlier age and helping them learn the delights of reading and writing? Maybe if they like it, more of them will go into it as a career.

    The best program I’ve seen for helping kids learn to love reading is the one Mary Leonhardt outlines in Keeping Kids Reading: How to Raise Avid Readers in the Video Age. It’s the culmination of the insights she gained over her thirty-five years teaching high school English and focusing on helping kids learn to LOVE reading. What an excellent book!

    Oh, and one other idea. It might be effective to maybe just skip publishers altogether and help folks go directly to readers as indie writers. Amazon’s algorithms are pretty much race- and gender-blind.

    Share
  • |

    Update and The Shape-Changer’s Wife

    Assassin is moving along. I’m heading into the last quarter of the book, which is where the fireworks start. I appreciate all of you who have been so patient. My goal is to end this arc of the series with a bang. 

    In the meantime, I’d like to recommend a fantasy novel. I enjoyed it many years ago and recently reread it, finding myself swept away with as much intrigue and delight as the first time. 

    It’s The Shape-Changer’s Wife by Sharon Shinn. 

    The story follows an aspiring wizard named Aubrey who is nearing the end of his training. He asks his mentor, the wizard Cyril, to teach him transmogrification—the art of changing form—but Cyril refuses. Aubrey protests. Cyril knows the spells. He has cast them himself. Still, he refuses. 

    Eventually, however, Cyril’s conscience gets the better of him. A well-rounded wizard should know every branch of magic, even the ones Cyril dislikes. So he writes to another wizard, a shape-changer named Glyrenden, and asks if he will take Aubrey as a student. Glyrenden agrees. 

    As Aubrey sets off, Cyril gives him a warning: “Learn everything he teaches you so well you can cast his own spells back at him. Glyrenden respects only those stronger than he is, and those he hates. If you cannot beat him, he will destroy you.” 

    And so begins the tale. 

    There’s mystery, wonder, betrayal, loss, battle, and even love. Best of all, it’s a complete stand-alone novel, a rarity these days. 

    If you’re hankering for a fantasy adventure that can be read in one volume, I think you’ll be very pleased with this one. 

    Happy reading,  

    John 

    Share
  • Short Reviews: Icefall, Gravity, 42, Z, and Lynda.com

    The last few weeks I’ve been burning the candles at both ends with publication tasks. So no time for long reviews, but I still wanted to share.

    Icefall by Matthew KirbyIcefall by Matthew Kirby

    Wow. I loved this book. LOVED IT! It’s Norse historical fiction. A war is coming, and the king sends his children away to a remote fjord steading to keep them safe. He also sends a number of trusted warriors, a company of beserkers, a cook, a thrall, and a skald. But the fjord isn’t remote enough.

    It’s a fine tale full suspense, wisdom, surprise, and two lovely character arcs. It’s told from the point-of-view of Solveig, the king’s plain daughter. And her voice and the details Kirby includes totally transported me to their world. A wonderful tale, wonderfully told.

    Gravity

    I don’t know if I like 3D very much, but Bullock and Clooney do a marvelous job. Do you remember Tom Hanks in the excellent Castaway where he’s marooned on a tiny island? This is Bullock’s Castaway, except the physics of space are deadly. A great film.

    42

    This film is about Jackie Robinson, the first Black man to play in the White leagues of American baseball, and recounts his first year. It stars Harrison Ford as the owner of the Brooklyn Dodgers, the guy who is determined to bring Blacks into the game he loves, as well as Chadwick Boseman who is new to me. I watched this with the whole family, and we were all enthralled. What a great story.

    World War Z

    I not a big zombie fan. So for me to recommend this means it had to be good. It was good. A delicious thriller with plenty of scare. I really liked the thriller feel to this. My wife and two youngest daughters sat on the couch holding each other’s hands. I sat in my La-Z-Boy throne heart pumping with the action.

    Lynda.com

    As I mentioned above, I’ve been working hard trying to get my books out the door. (Please, boys, just get out! It’s time for you to make your way in the world!) I’m using Adobe InDesign to format them for Kindle and EPUB, but I barely know the program. That caused some big problems. But then I subscribed to Lynda.com–a training website. I can’t tell you how happy I am that I did.

    For $25 per month (and you can just subscribe for one month), you get access to hundreds of high-quality online classes recorded by experts. Each class is usually a few hours long, made up of videos that are usually each shorter than ten minutes. The site allows you to create playlists of various courses you want to take, makes recommendations, and lets you know which videos in a class you’ve watched. It also includes a verbatim transcript so you search for the part of the video that’s interesting to you.

    The workhorse I’ve been using is “InDesign CS6 to EPUB, Kindle, and iPad” by Anne-Marie Concepcion. It’s 7.5 hours long.  I’ve also been referring to parts of “InDesign CC Essential Training” by David Blatner and “Creating Long Documents with InDesign” by Mike Rankin. And I have 16 other courses in my playlist that I can’t wait to get to like “Designing a Book Cover” by Nigel French and others on graphic design, typography, and logos.

    If you need training on some software product, go out to Lynda.com and see if they have a course for you.

    Share

4 Comments

  1. More people need to know this kind of stuff and use it. I don’t like using spreadsheets, and tried out a number of budgeting applications before finally settling on YNAB. It’s the most useful software tool for planning expenses that I’ve found, and it follows all the principles you’ve talked about here. I highly recommend it.

  2. Thanks for posting this. It’s very timely for me. I visited Dave Ramsey’s site after I read your post. I’m ready to start the baby steps. 🙂

Comments are closed.