For your epic enjoyment

On Writing Excuses someone talked about writing an epic fantasy in a limerick. I figured I’d give it a go. Of course, it’s a slight cheat, but epic nevertheless.

A tiny man with a ring
Said I’ll save the world from this thing
He traveled to Mordor
But in very short order
Was trounced by the chatty bling bling

Share

Similar Posts

  • AIG bailout, risk, and writing

    With the current financial “crisis” I kept wondering what went wrong. Read this article on the AIG mess from the guys at the Motley Fool. That explaination of the AIG mess is very interesting. The other part of this current financial mess, the loaning-of-money-to-people-who-were-idiotic-credit-risks and the making-me-foot-the-bill-for-someone-else’s-assumption-of-ridiculous-risk, those two parts torque me.

    So why am I posting this in the Zing and Writers categories?

    Because it IS zing to me. You could write a high-finance thriller about this. You could write about a character who leveraged himself silly and is about to lose it all–in a smaller sense. You could write, hey, wait a minute. I just read a book about something similar–THE CHAIRMAN by Stephen Frey. It’s a 2.5/5 star book. Good enough that I had to finish it. Although not good enough to make my recommendation list. 

    The point is that stories are about problems and conflicts. And this understanding of the insurance industry provides some fertile ideas for both problems and conflicts.

    And since I can’t get the blasted link to work, here’s the full deal.

    AIG’s Failure Is So Much Bigger Than Enron
    By Andrew Sullivan, CFA
    September 17, 2008 Comment (54) Recommend (124)
    Enron — reviled, fraudulent Enron — destroyed more than $60 billion of shareholder value.

    AIG (NYSE: AIG), which the government just took over, has destroyed $180 billion already — and it almost brought down our entire financial system.

    We don’t know money
    Which is ironic, given AIG’s old television commercials, in which the giant letters “A I G” displayed on the screen while text flashed underneath that culminated in the following phrase — all in capital letters:

    WE KNOW MONEY

    There were no smiling couples, young children at play, or lounging retirees. No, AIG was above that — it was better than that.

    But here’s a news flash, AIG: You don’t know money.

    If you did, you’d have realized a few things. Insurance is terribly simple, as long as you follow the Three Rules:

    Price your risk correctly.
    Invest conservatively so you can pay out claims when they come due.
    Don’t do anything else.
    Sit back and collect the spread. That’s it, folks.

    Seriously, that is it. Ask Warren Buffett, and he’ll probably tell you that if you follow those three rules, you’ll be fine. You won’t be the biggest or fastest grower, but you’ll be absolutely fine.

    The problems come when you get greedy and aren’t satisfied with the spread. And your greed can lead to certain actions that aren’t stated anywhere in the rules, including:

    Diversifying into fast-money proprietary trading.
    Leveraging your company 11-to-1.
    Neither of these is a goal of a well-run insurance company, yet AIG embraced both with open arms.

    Diworsifying
    But AIG self-destructed not because it screwed up in its insurance business. It didn’t fall into the trap of mispricing risk, as so many other insurers over the years have done. It also invested premiums fairly conservatively. So it followed Rules 1 and 2.

    Where it slipped up was in Rule 3. See, the folks at AIG thought they were so smart at insurance that they could start other capital-markets businesses … including proprietary asset management in things such as commodities, currencies, energy, interest rates, and the selling of default swaps on collateralized debt obligations (CDOs).

    This strategy worked beautifully — for a while. AIG created a separate business segment called Financial Services to trade in the aforementioned assets. This business had $204 billion in assets at year-end 2007, up from $60 billion in 1998.

    Operating income surged from $900 million in 1998 to $4.4 billion in 2005. Some of the moves it made were brilliant, such as the purchase of ILFC, an aircraft-leasing business. But the other trading businesses were the Medusa that turned the whole company to stone.

    Let me make one thing clear: Proprietary trading isn’t bad, in and of itself. Warren Buffett engages in it. But just like atomic weapons in the wrong hands, proprietary trading can do a lot of damage. The problem is when you start to get aggressive and don’t heed proper risk — when you start to speculate instead of invest.

    And there’s one other critical ingredient for disaster.

    The “L” word
    As in “leverage,” the sharp knife in corporate seppuku dramas. Leverage is, by my estimation, the No. 1 reason why companies fail.

    And compared with its peers, AIG had one of the sharpest knives around. Here’s how its leverage (assets to equity) stacked up against other insurance operations as of December 2007:

    AIG: 11 to 1.
    Markel (NYSE: MKL): 4 to 1.
    Berkshire Hathaway (NYSE: BRK-B): 2 to 1.
    Montpelier Re (NYSE: MRH): 2 to 1.
    Travelers (NYSE: TRV): 4 to 1.
    White Mountains Insurance (NYSE: WTM): 4 to 1.
    Chubb (NYSE: CB): 4 to 1.
    I would love it if someone gave me a rational, believable explanation of why leveraging your equity 11-to-1 is a good thing for an insurer. The sole job of an insurance CEO is to ensure that his or her company stays in business; the CEO’s job has nothing — absolutely nothing — to do with growing profits every year in a steady, smooth line.

    Surprises in insurance are almost always negative, so simply staying solvent is the overriding priority. A company can do just that by following the Three Rules.

    Two years ago, a few of my Fool colleagues had an interesting conversation with Chris Harris, the chief investment officer at reinsurer Montpelier Re. Harris noted that Montpelier invested its float primarily in U.S. Treasuries, Fannie and Freddie bonds (back when they were considered safe), and the like.

    When asked why he didn’t invest more aggressively, Harris said the company believed that it got all the risk it could handle on the other side of the fence, insuring against megacatastrophes.

    Even if you disagree, as an investor you have to recognize the judiciousness in this way of managing one’s business. An insurer that has to pay big claims from hurricanes Ike and Gustav and Typhoon Sinlaku — and additionally worry about the rapid decline in its investment portfolio as a result of the higher level of risks it has taken on — has a big problem.

    That insurer, folks, is AIG. And that big problem is now yours and mine.

    This really is bigger than Enron
    The edifice Hank Greenberg built has all come crashing down. Apparently, AIG didn’t realize that almost 40 years of 15% growth multiplied by a big fat zero equals just that: zero. It didn’t consider that its leverage left it exposed to a liquidity crisis, and it didn’t consider that its non-insurance businesses could bring down the whole company.

    In all fairness, management did not realize how much exposure it had to CDOs backed by subprime loans. This may or may not be true, but Buffett has famously stated that each one of these prospectuses has something like 15,000 pages, so it’s unlikely they were gone through in any great detail.

    But investing in things you don’t know is a huge risk, right? And that risk was compounded by having so much leverage. The fact is, the more leverage you have, the more careful you must be with the investments you hold, because your own capital structure is that much riskier.

    AIG did nothing of the sort. And so even though it has a rock-solid, wonderful insurance franchise, its greed and lack of care in its investing decisions took down one of the world’s great companies.

    What a shame. What a shame for all of the investors who lost billions thinking that this company was conservative. What a shame for taxpayers like you and me. What a shame for the United States’ reputation as a beacon of financial stability and conservatism.

    For Fool.com’s continuing coverage of this week’s events, check out “The Biggest Financial Story of the Past 50 Years.”

    Andrew Sullivan has no financial interest in any of the companies mentioned. Montpelier Re is a Motley Fool Hidden Gems selection. Markel and Berkshire Hathaway are Motley Fool Inside Value recommendations. Montpelier Re and Berkshire Hathaway are Motley Fool Stock Advisor picks. The Motley Fool owns shares of Berkshire Hathaway and has a disclosure policy.

    Share
  • |

    This American Life: Superpowers

    What superpower would you rather have–flight or invisibility? What do others choose? Why? What does it say about you?

    Want to hear about a gal named Zora who, as a teen, made a list of everything that a superhero would have to know how to do, things like flying helicopters and diffusing bombs, and then set out to do it. Zora finished her list, btw. She’s a bounty hunter now.

    You can hear this right now on  This American Life episode 178: Superpowers .

    It’s a fabulous hour-long program.

    Share
  • Mumma, Cat of Death

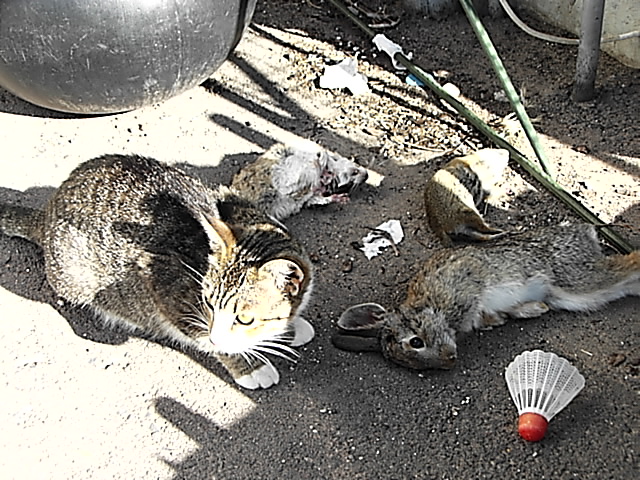
    PIC02680

    I figured regular readers would want a break from all the book release news, as fascinating as it is. And so I present to you my photograph, “Mumma, Cat of Death.” (I need a new camera. The quality of this piece of junk is so stellar.)

    Mumma was a stray that showed up in our garage one day, freaked many of the long-timers, and then got pregnant. Up here in the ranch lands there are no such thing as spaying and neutering. There are a number of Toms, and, well, we were too slow with our communist population control program. So she had five cute kittens. Up until that time she was satisfied with catfood and an occasional bird or mouse. After that, she became Mumma, Cat of Death.

    What you see above is only PART of the catch of ONE day: a packrat, a ground squirrel, a bird (she ate it, what you see on that piece of white paper is what she left–one leg), and a rabbit. Notice, she’s looking away from her catches. I think she was eying a visitor’s toddler at that moment, deciding if she could take him down. Every day she hunted up a few meals. And these were not for show, not nice gifts left on the doorstep for the master. No, she’d bring them up from the fields, let them ripen a bit, and then start in at the head. But she wouldn’t always eat the whole thing. Sometimes she’d leave it for the kittens. Sometimes, she’d just leave it for the next day. She turned our garage into a scene of blood and carnage.

    So again: Mumma, Cat of Death.

    Share
  • |

    Buffett’s Letter to Berkshire Hathaway Shareholders on 2008

    I got my masters degree in accounting and information systems. While going to school I started an investment club and learned about a man named Warren Buffett.

    Warren Buffett is humble, full of folksy humor, and trades places with Bill Gates as the richest man in the world, depending on the year you’re counting. His annual letters to his shareholders are a delight to read. This year’s is full of wisdom about the current financial crisis. Moreover, within a few minutes of reading you will be able to get some key insights that can help as you evaluate the plans being hatched in Washington and how to prevent this particular type of crisis from happening again. 

    If you’re not that into finance, I recommend reading:


    1. The introduction starting on page 2 and ending on page 3
    2. The “Finance and Financial Products” section starting on page 10 and running through page 12

    Once you’ve read those, if you want to laugh and see Buffet’s humor, skip to page 21 where Buffett talks about the annual meeting of shareholders. Tell me you wouldn’t want to attend.

    The Berkshire Hathaway homepage

    This year’s letter to shareholders (you will click on 2008 because he’s discussing the results of that year)

    Share
  • Uncanny cool

    I just had the most uncanny, coolest experience. It’s 6 PM. I’m out on a walk along a road that runs by a swampy river called Birch Creek to a fork in the road. The sky is this glorious blue with brilliant white and gray clouds. I stop and pick some ripe black currents off a little spindly bush growing down off the shoulder in the rocks and continue on.

    I take the left fork, south along the hill and enjoy the sight of the mown fields, a scattering of green ton bales standing on the short meadow grass, and the storm clouds gathering over the hills to the west.

    A few rabbits spook and run across the road. I reach the mile mark and turn back. I’d already done 30 minutes worth of shred before the walk and needed to get back to practice basketball with my oldest. The whole time I’m listening to Lois McMaster Bujold’s HALLOWED HUNT read by Marguerite Gavin. It’s warm, sunny, lovely. The story is good.

    I come back by the fork and hear this sound over the audio. It’s like a single prop airplane in the distance. I continue on another hundred yards. That distant, thin drone grows, but I can’t figure out what it is, so I put the audio book on hold and take off the ear phones.

    The air is perfectly still. That muggy stillness that precedes a storm. But all around me is this sound. This thin drone, filling up road. It’s coming from all sides.

    Insects?

    I look down off the side of the road at the sloughs and cattails and willows and see nothing. I look back up. Look around. And then I notice a small black body speed past. And another. And another.

    Flies? It can’t be flies. When have you ever seen a fly pursue a straight line?

    Three more. Half a dozen. Another, another, and they’re everywhere. But they’re not flying thickly. Not mobbing. Not massed in some cartoon clump. They’re all spread out. I strain to see them in this odd light.

    Bees. They’re dark. Almost black in their flight, but it has to be bees!

    And they’re all around, thirty feet to either side of me. Zooming past. There, there, and there. It’s like dozens and dozens of refugees in flight with single purpose. There’s no looping around. No dalliance. No crazy panic. They’re serious, focused. All of them going the same way. Straight ahead on some urgent goal.

    There’s a big fat blue dragonfly in the willows that keeps zipping after individual bees as they fly past, trying to get a meal, but each time, just at the moment when it would attack, it spooks and darts back for cover. Dragonflies are voracious buggers. But these aren’t single bees. It must be thinking the other bees are coming for it. Still it can’t resist and darts out again.

    And all around is the humming. It grows. The bees directly in front of me see me as they approach and make course corrections. I keep walking. A half a mile and the thin droning still surrounds me. The bees keep coming, but they’re thinning.

    Thunder cracks behind me. The wind begins to pick up. The sky behind me is darkening.

    The sound of the drone grows thinner, is almost gone. But there are bees still out there, following. I can hear them. See them. Individuals trailing the others, flying past me toward the storm that’s still about a mile off. And I think they’re too far behind.

    Maybe their hive was wrecked. Maybe it’s just time to swarm and there’s a queen up front leading them. And somehow her scent is on the wind. Somehow they know to follow.

    I don’t know if they’ll find a new place. They’re going to have to cross a mile of mown meadow before they get to anything that might serve as any type of shelter. I don’t know if the wind will ground them, or the main group will find safety but the stragglers will be blown to their deaths. All I know is that I’m sitting here in awe, electric with life.

    Share